
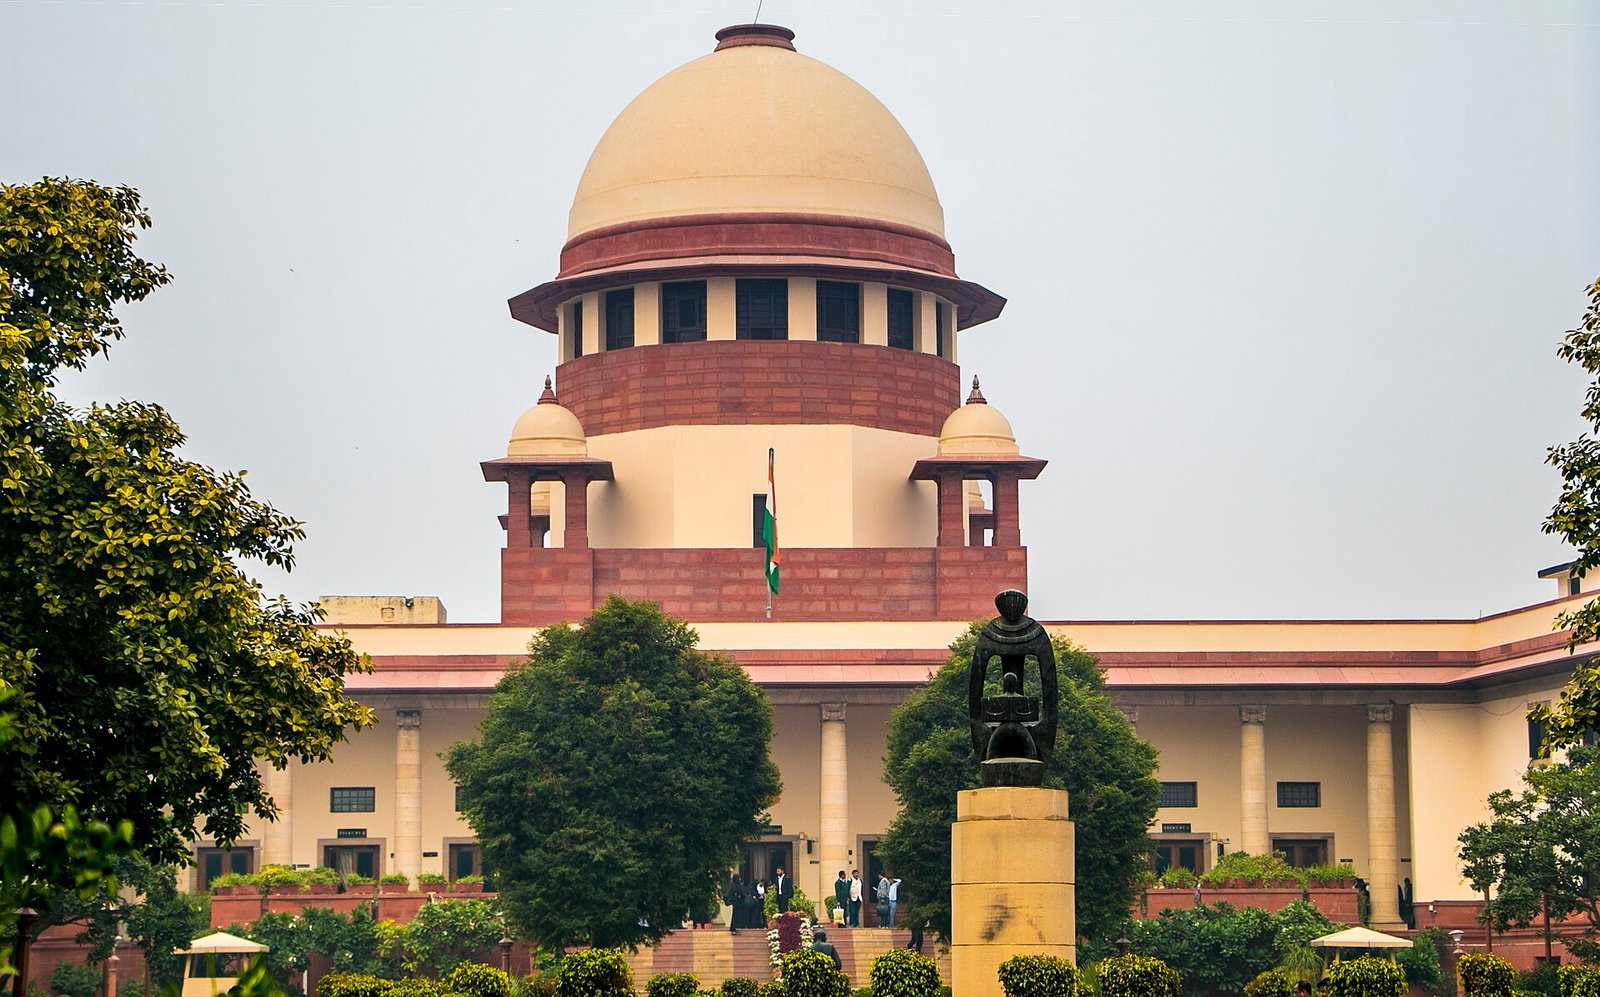
India’s Supreme Court has ruled that YES Bank’s 2020 write-off of its Additional Tier 1 bonds was unlawful. On October 15, a bench of Justices Dipankar Datta and Augustine George Masih dismissed appeals by YES Bank, its administrator, the Reserve Bank of India and the Union of India. That upholds a Bombay High Court order of January 20, 2023, which struck down the write-down.
Two bond series were at stake: ₹3,000 crore issued in December 2016 with a 9.5% coupon, and ₹5,415 crore issued in October 2017 with a 9% coupon. The administrator wrote both down on March 14, 2020, a day after the government notified YES Bank’s reconstruction scheme.
The ruling turns on who held the power. The final scheme dropped a write-down clause that had appeared in the draft, and the court held that a general savings clause could not supply a specific power to write the bonds down. Under the RBI’s master circular, it said, the power to write down bonds at the point of non-viability belonged to the RBI, not the administrator. “Any act performed by the administrator beyond the powers clothed upon him would be wholly illegal and void,” the judgment says. The bench judged the decision as of March 14, 2020.
The court was pointed about the regulator. “The RBI was a mere bystander, allowing the CET1 ratio of YES BANK to drop to an astonishing low of 0.6%,” the judgment says. That was the bank’s common equity tier 1 ratio at December 31, 2019, against a requirement of 7.375%.
On coupons, the court said payment of the annual coupon “shall remain unaffected by the outcome of these appeals” and must be made under the bonds’ information memoranda. Each party bears its own costs, and the court said its observations are limited to these appeals, so other pending proceedings can continue.
Herald View
For bondholders, the most practical line in the judgment is on coupons, which must be paid under the original terms. At the stated rates, that is about ₹285 crore a year on the 9.5% series and about ₹487 crore on the 9% series, roughly ₹772 crore combined. The wider consequence is for resolution practice. The court accepted that AT1 can absorb losses. Its objection was that the write-down came from the administrator, under a scheme that no longer contained the power. Future RBI-led rescues will need the write-down written into the scheme and executed by the RBI before reconstitution. That should, over time, reduce the legal risk premium Indian bank AT1 has carried since 2020. Spreads on outstanding AT1 issues are the place to watch.
